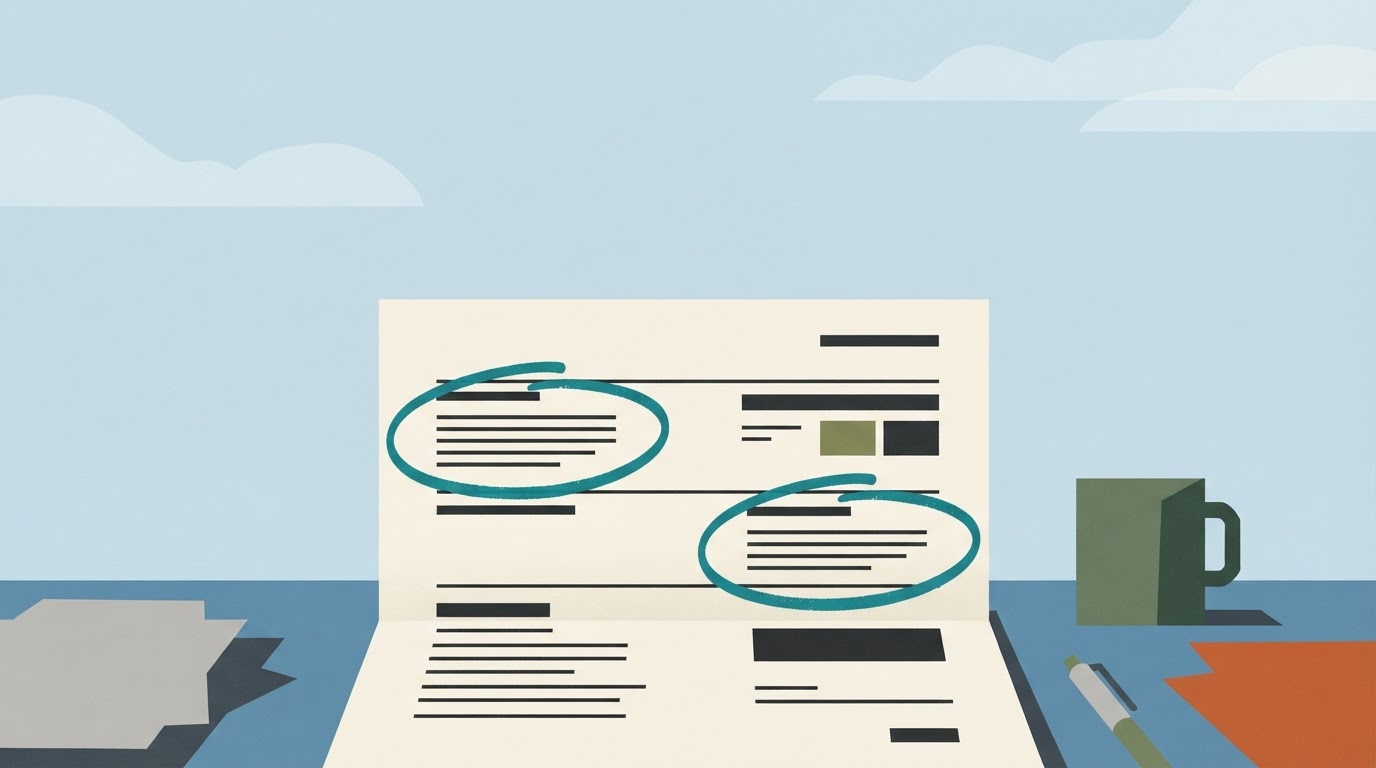
Pull out your declarations page – the summary sheet at the front of your policy packet, usually one or two pages – and look at the section labeled “coverages” or “premium breakdown.” If you have physical damage coverage on your vehicle, you may notice the word “deductible” appears more than once, each time next to a different dollar figure. This is not a printing error, and it is not a sign that your insurer is trying to confuse you. It reflects the fact that your policy is really several distinct coverages bundled under one contract, and each one can be priced and structured on its own terms.
Why some policies list more than one deductible
A deductible is the amount you agree to pay out of pocket before your insurer contributes to a covered loss. It exists on coverages where the size of the loss is variable and something the policyholder can influence to some degree – mainly the coverages that pay to repair or replace your own car. Deductibles generally do not apply to liability coverage, which pays for injuries or damage you cause to others, because that coverage is not about repairing your own property.
Your policy likely bundles together several coverages that behave differently:
- Liability coverage (bodily injury and property damage to others) – no deductible
- Collision coverage – typically has its own deductible
- Comprehensive coverage – typically has its own separate deductible
- Optional add-ons like rental reimbursement or roadside assistance – structured differently, sometimes with caps rather than deductibles
Because collision and comprehensive are legally and actuarially treated as separate coverages, each one carries its own deductible line on the declarations page, and insurers allow you to set them independently rather than forcing you to choose one number for both.
Comprehensive vs collision deductibles
The two deductibles you’re most likely to see side by side belong to comprehensive and collision coverage. They sound similar and are often purchased as a pair, but they respond to different kinds of events.
Collision coverage pays for damage to your car that results from it hitting, or being hit by, another vehicle or object – a crash with another car, sliding into a guardrail, hitting a mailbox while backing out of a driveway. The common thread is that your car was in motion and made contact with something.
Comprehensive coverage (sometimes called “other than collision” in policy language) pays for damage from causes not involving a collision: theft, vandalism, fire, a tree limb falling on the car, hail, flooding, or a deer running into your path. Despite the name, comprehensive is not a catch-all for every possible loss – it specifically covers the category of non-collision events your policy defines.
Because these two coverages respond to different risks, insurers price them separately, and you’re generally allowed to select a different deductible for each. It’s common, for example, to see a lower deductible for comprehensive claims and a higher one for collision claims, or vice versa, depending on how a policyholder weighed cost against risk when the policy was set up.
How to tell which deductible applies to which claim
When damage happens, the deductible that applies depends on how the loss is classified, not on which number is smaller or which one you’d prefer. A few practical ways to sort this out:
- Read the declarations page labels carefully. Most insurers list the deductibles right next to the coverage name – “Comprehensive Deductible: [amount]” and “Collision Deductible: [amount]” as separate lines. If your page only shows one deductible amount, it may mean you only carry one of the two coverages, or that your insurer uses a single combined deductible – worth confirming rather than assuming.
- Think about what caused the damage, not just what the damage looks like. A cracked windshield from a rock kicked up by a truck is comprehensive. A cracked windshield from swerving into a tree is collision. The visible damage can look identical; the cause determines the coverage.
- When a claim involves both categories, insurers sort it out during the claims process. If you swerve to avoid an animal (comprehensive-type event) and then hit a fence (collision-type event), the adjuster handling your claim will determine how the loss is classified and which deductible or deductibles apply. This is one of the reasons that filing a claim promptly and describing the sequence of events accurately matters – the classification is based on what happened, not on how you’d like it categorized.
- Check for special deductible waivers. Many policies waive the comprehensive deductible specifically for glass repair, since chip repair is inexpensive and insurers want to encourage small fixes before a crack spreads. If your policy has this feature, it will usually be noted separately, sometimes as a “glass deductible” or “full glass coverage” endorsement.
If you’re ever unsure which deductible will apply to a specific incident before you file, your insurer’s claims department or your agent can generally tell you how a described scenario would be classified. This is worth doing before a repair estimate is written, since it affects what you’ll be asked to pay upfront.
Why matching deductibles isn’t required
Some drivers assume their comprehensive and collision deductibles must be the same number, since both coverages deal with damage to the same car. They don’t have to match, and insurers don’t typically require it. A few reasons this flexibility exists:
- The coverages carry different risk profiles. Comprehensive claims – hail, theft, falling objects – are often smaller in dollar terms and less within the driver’s control. Collision claims tend to correlate more with driving behavior and traffic exposure. Insurers price and structure them separately because the underlying risk is different.
- It lets you tailor cost to your own risk tolerance. A driver who parks on the street in an area with frequent break-ins or severe hail might choose a lower comprehensive deductible, accepting a higher premium for that coverage in exchange for less out-of-pocket exposure on the claims that worry them most. The same driver might set a higher collision deductible if they consider themselves a low-risk driver and want to save on that portion of the premium.
- Lowering your out-of-pocket cost on one coverage generally raises the premium tied to that coverage, and raising it lowers that premium – again, independently for each. Because the two deductibles are priced separately, adjusting one doesn’t automatically affect the other.
- State rules generally don’t dictate deductible matching. While states regulate what liability limits must look like at minimum, deductible structure on physical damage coverage is largely a matter of contract between you and your insurer, within the deductible options that insurer offers.
If your declarations page shows two different numbers, that’s typically the result of a choice – either one you made when you set up the policy, one your agent set as a default, or one that carried over from a previous policy term. It’s worth reviewing whether those two numbers still reflect how you’d want to handle a claim today, especially if your circumstances or vehicle have changed since the policy was first written.
A quick way to check your own page
Next time you have your declarations page in hand, look for these things specifically:
- Is there a line for comprehensive coverage, and does it list its own deductible?
- Is there a separate line for collision coverage, with its own deductible?
- Are the two numbers the same or different, and does that match what you remember choosing?
- Is there any note about a glass deductible waiver or other special deductible handling?
None of this requires contacting your insurer to understand – it’s usually printed in plain enough terms once you know what you’re looking for. But if anything is unclear, or if you’re not sure whether you’re even carrying both comprehensive and collision coverage, your agent or insurer’s customer service line can confirm what’s actually on your policy. Knowing the answer before you ever need to file a claim means one less thing to sort out at a moment when you’re already dealing with a damaged car.